Indians trapped in repayment chakravyuh as loan apps fuel endless borrowing cycle
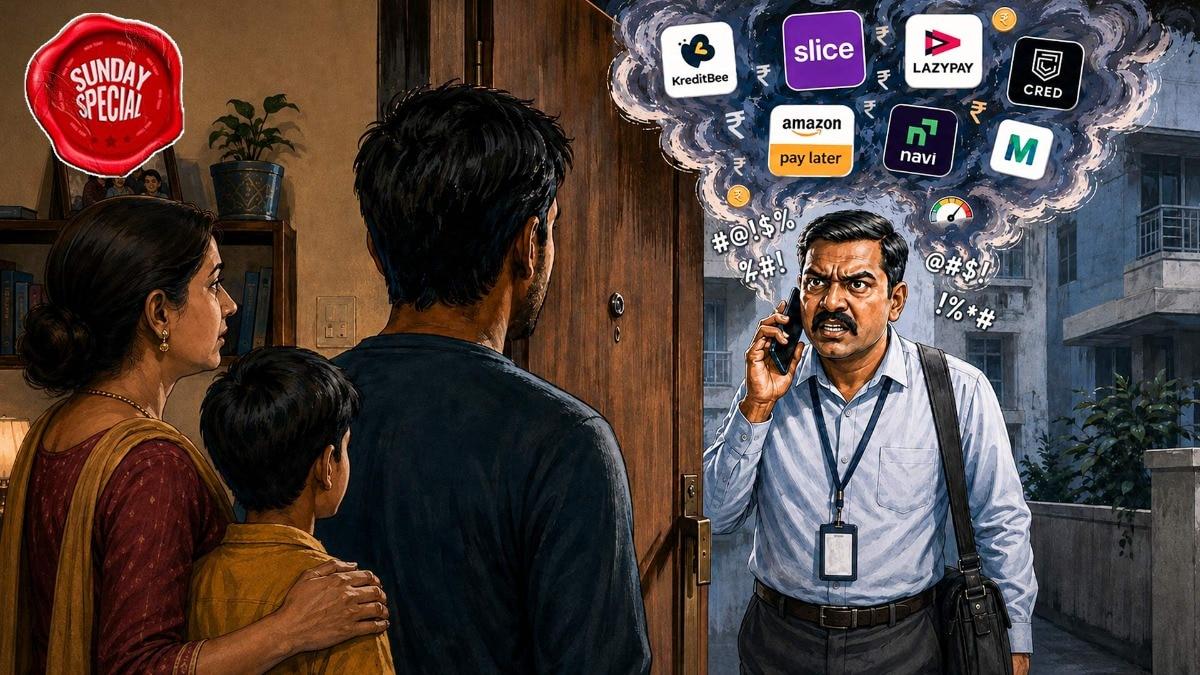
In India, the rise of instant loan apps has led to a troubling cycle of debt for many households. What begins as a small, seemingly manageable loan can quickly spiral into a financial crisis. For instance, Rishabh Shukla, an engineer, initially borrowed a modest amount to support his studies. However, as he continued to rely on these apps for various expenses, he found himself trapped in a cycle of borrowing to repay previous loans. The ease of accessing credit through a few taps on a smartphone often masks the long-term consequences of such decisions. The situation is exacerbated by stagnant incomes and rising living costs, pushing many young professionals to take on debt that outstrips their repayment capacity. Recovery agents like Suresh Gowda observe that many borrowers, often students or early-career workers, struggle to keep up with their financial obligations, leading to sleepless nights and anxiety. The pressure to maintain a lifestyle showcased on social media further complicates matters, as individuals feel compelled to spend beyond their means. As the digital lending market continues to grow, with apps now accounting for a significant portion of personal loans, the risk of falling into a debt trap increases. This trend highlights the urgent need for financial literacy and responsible borrowing practices to protect vulnerable households from the pitfalls of easy credit.
Comments